October 6, 2026
Tech Resiliency Masks Underlying Market Divergence
Equity markets delivered a split performance in September. The S&P 500 slipped 0.5% for the month, while the tech-heavy Nasdaq gained 1.9%. After three quarters we are on the verge of another year of double-digit gains with the S&P 500 up 11.8% and Nasdaq at 15.6%.
As of this writing in the first week of October, the S&P 500 and Nasdaq are trading at all-time highs.
Headline index numbers masked significant weakness across the broader market. Small-cap stocks dropped 5.3% and 83% of S&P 500 components traded down more than 10% from their 52-week highs in September, according to Bloomberg.
Sector performance highlights this narrow leadership. Communication Services, led by Meta and Alphabet, along with Information Technology, were the only S&P 500 sectors to finish September in positive territory. The tables below depict the weakening breadth of the large-cap indexes.
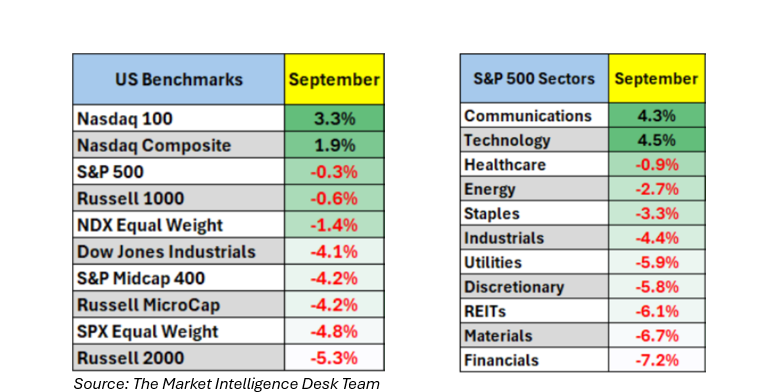
Despite the broader market drag, solid economic fundamentals continue to support corporate America. Unemployment ticked up slightly to 4.2%, but consumer spending, hiring, and manufacturing data remain at healthy levels. Third-quarter GDP growth continues to run at a robust pace.
Bond yields have surged over the past month with the 10-year U.S. Treasury hitting 5.31%. This is the exact rate scenario we cautioned as the biggest risk to equities, yet stock prices continue to power through, driven by robust corporate earnings and economic momentum.
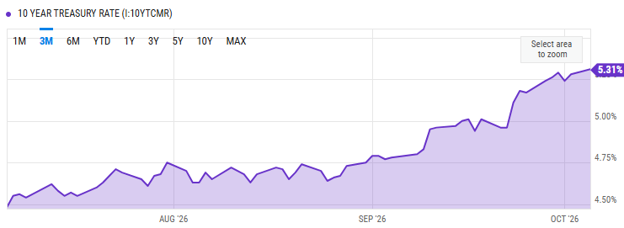
Bond yields are rising due to a long list of reasons. We feel this is a unique time where many binary forces are all pushing the same direction: Strong U.S. economy, sticky inflation, elevated U.S. deficits, corporate bond issuance for AI infrastructure, the Japanese yen carry trade unwinding, new Fed leadership lacking credibility, a lack of progress in talks with Iran, and ongoing energy supply pressures stemming from Middle East tensions.
With yields moving upward, the average 30-year fixed mortgage rate reached 7.03%, marking its first move above 7% since early 2025. This threshold should not impact equities heavily, as this bull market has run through a frozen housing market for a couple of years now, along with other major macro events and trends like tariffs, wars and inflation.
We believe the market’s resilience boils down to two core macro drivers: AI infrastructure buildout and massive government deficit spending.
Tech capex is projected to surge from roughly $380 billion in 2025 to $1.3 trillion in 2027, injecting over $900 billion mostly into the domestic economy.
While running a $2 trillion annual federal deficit is fiscally irresponsible and fuels inflation, this continuous injection of capital provides a short-term boost to broad economic activity and corporate revenue growth.
This combined ~$3 trillion in spending will serve as a massive liquidity engine, continuing to propel GDP growth and insulate corporate profits. Inflation and higher rates will continue to apply counteracting pressure.
We are optimistic that the good times can continue. As stock prices have climbed, valuations have come down. The S&P 500 forward P/E currently stands at 18.9x compared to a year ago when it was 23x, according to Yardeni Research.
The valuation compression is likely rooted in investors’ skepticism that the capex spend can continue. Simply put, the market doesn’t believe the earnings and margins can be this good for an extended period. This sobering view decreases market risk and leaves plenty of room to the upside if Wall Street’s forward earnings projections are accurate.
Looking ahead, the bond market and pending Anthropic IPO could put stress on stocks in October. Downside risk has increased due to higher rates. Midterm elections may fuel some temporary narratives and change the mechanics of governing, but the executive branch initiatives that impact the economy like tariffs and other key policies will persist.
Overall, we remain in a healthy bull market that is accommodative to investors, with normal bouts of volatility.
We are honored and thankful for your trust and are always available for a conversation regarding investments or planning.